• Sight Deposits in RSD

    Sight savings now with up to 4.01% annual interest.

    • · 2.01% per year in the standard offer
    • · 4.01% per year when you receive your salary into a Yettel Bank account
    • · Your money is always available and you can withdraw it at any time
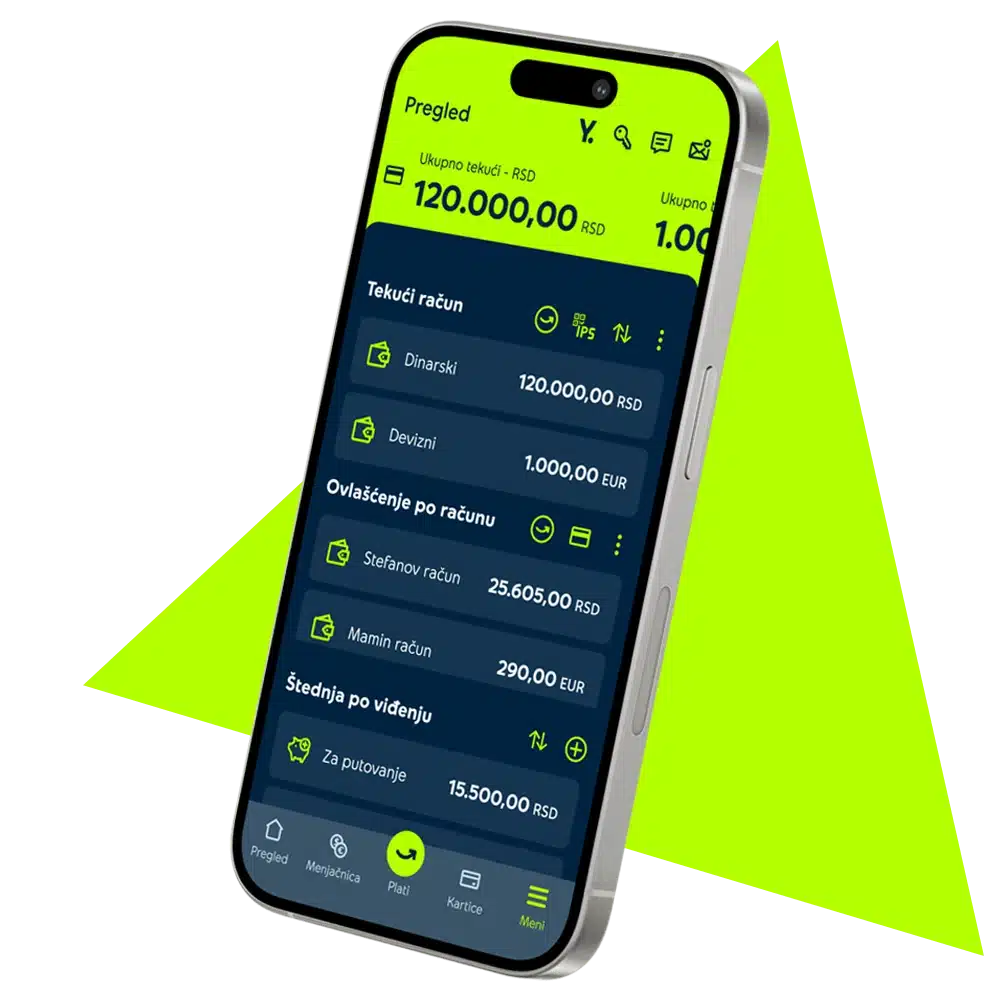
    • · You do everything in the app
    Open savings in the app

4.01% per year when you receive your salary

If you receive your salary into a Yettel Bank account and open a new sight savings account from 28 October 2026. It consists of a contracted interest rate of 0.01% and a bonus interest rate of 4%.

START SAVING

2.01% standard offer

The interest rate for sight deposits in RSD. It consists of a contracted interest rate of 0.01% and a bonus interest rate of 2%.

START SAVING

The 4.01% interest rate is available in the latest version of the Yettel Bank app.
If you can’t see it, update the app and open a new sight savings account in just a few minutes.

What do you get with both offers?

Money always available

Move money from your savings to your current account whenever you want, with no fixed term.

No amount limits

There is no minimum or maximum amount, and you can open more than one savings account.

Every day of saving counts

Interest is calculated for every day your money is in the savings account and credited at the end of the month.

No tax on interest

No tax is paid on interest on savings in dinars.

How to start sight savings?

1

Download or open the app

Download the Yettel Bank app, or log in if you already use it.

Download APP
2

Open a savings account

Choose sight deposit in RSD. You will see the interest rate that applies to you before you confirm.

3

Transfer money

Transfer money from your current account to your savings account with an internal transfer. Interest is calculated for every day your money is in the savings account and credited at the end of the month.

To get 4.01% per year, all you need is to receive all or part of your salary into a Yettel Bank account. Receiving your salary at another bank? Fill in the salary transfer authorisation and hand it to your employer.

Your money is always available.

There’s no need to keep your money locked away in an account when you can access your growing savings every month.

Open savings in the app

More goals? Open more savings accounts online in the app.

At Yettel Bank you can have more than one sight savings account and name each one after the goal you’re saving for.

Opening and managing your savings account is done online, so you can move money from savings to your current account and back at any time. You can also open several accounts for different savings goals. If you don’t have an account, just open one and you’ll be able to do everything through the mobile app.

Open savings in the app

How to open a Yettel Bank savings account?

Simply, quickly and directly through the Yettel Bank mobile app!
No paperwork and no waiting – a few clicks and your savings account is ready.

Save every day, with your money always available!

Open your account and manage it in the app.

Start saving now

Need help opening your savings?

Leave your contact details and our agent will call you and help you open your account and savings and transfer your salary.

YettelBank_ThankYou_Image

    Name and surname*
    Phone number *
    Email *
    Place of residence *

    At the following link you can read the Notice on the processing of personal data

    The collected user data will be used exclusively for the purpose of calling for additional information in the pre-contractual phase about the conditions of our Bank’s products.

    Your application for RSD sight deposits has been received!

    You can expect a call from our agent shortly to complete the process of opening your savings account.

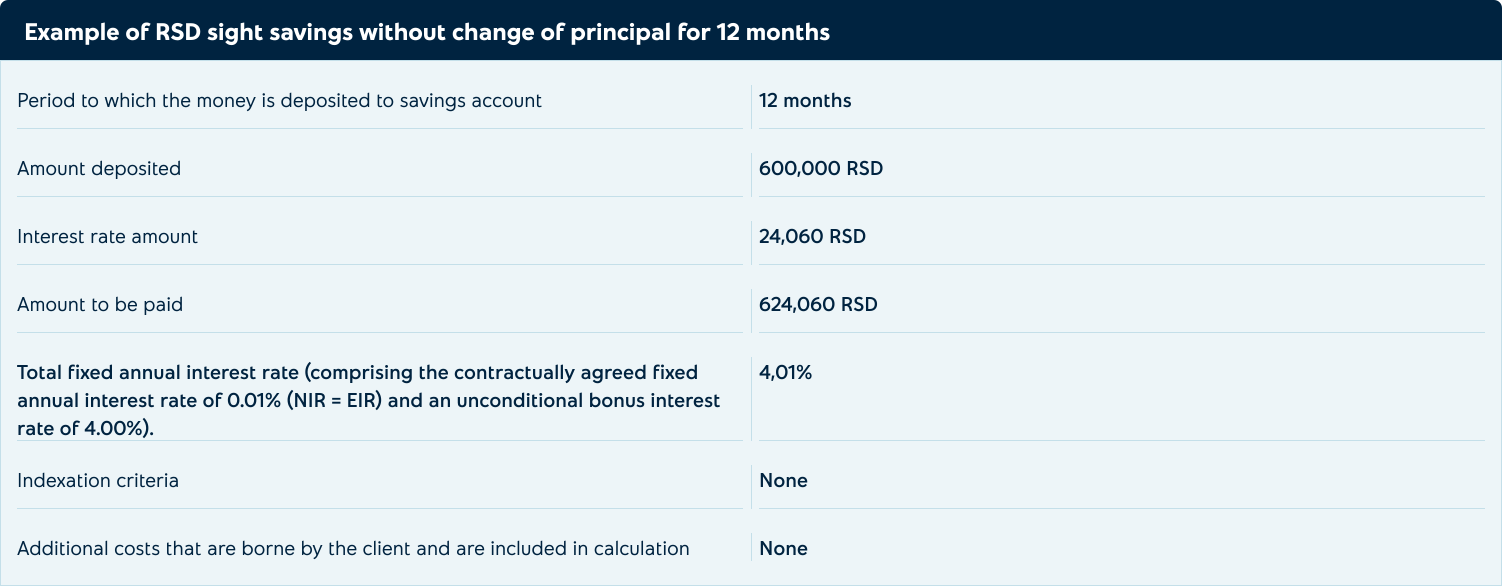
    Representative examples for the 4.01% interest rate with salary received into a Yettel Bank account

    Representative example of Yettel Bank savings without change of principal for 12 months

    The example was made on the assumption that the money was deposited to a savings account on 1 October 2026. The example was made on the assumption that the additional benefit in the form of Bonus Interest remains unchanged in the period for which the calculation was made.

    In the example shown, the savings interest is calculated on the assumption that the account balance remains unchanged for 12 months, without any increase or decrease in deposits. No tax is applied to interest on savings in dinars.

    The representative example was created by applying the contracted NIR and Bonus interest rates, which are calculated and paid together. The example is for information purposes only.

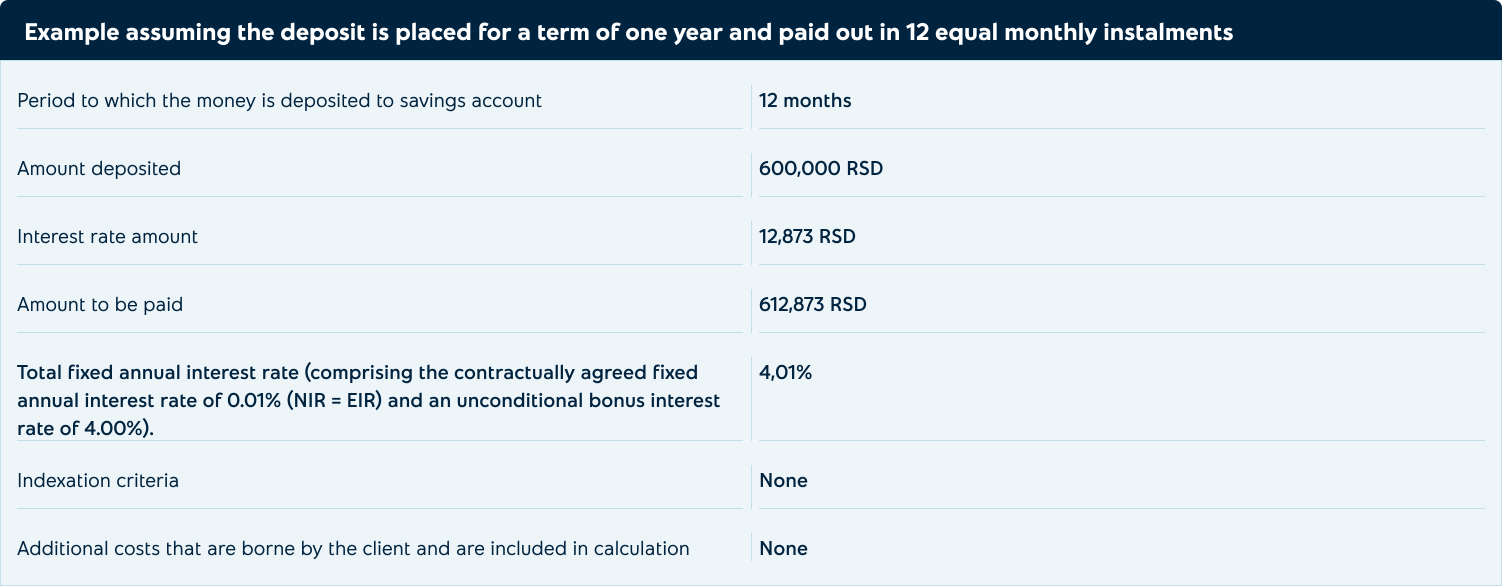
    Example of Yettel Bank savings, assuming the deposit is fixed for a one-year period and paid out in twelve equal monthly instalments

    The example was made on the assumption that the money was deposited to a savings account on 1 October 2026. The example was made on the assumption that the additional benefit in the form of Bonus Interest remains unchanged in the period for which the calculation was made.

    In the example shown, the savings interest is calculated on the assumption that the account balance remains unchanged for 12 months, without any increase or decrease in deposits. No tax is applied to interest on savings in dinars.

    The representative example was created by applying the contracted NIR and Bonus interest rates, which are calculated and paid together. The example is for information purposes only.

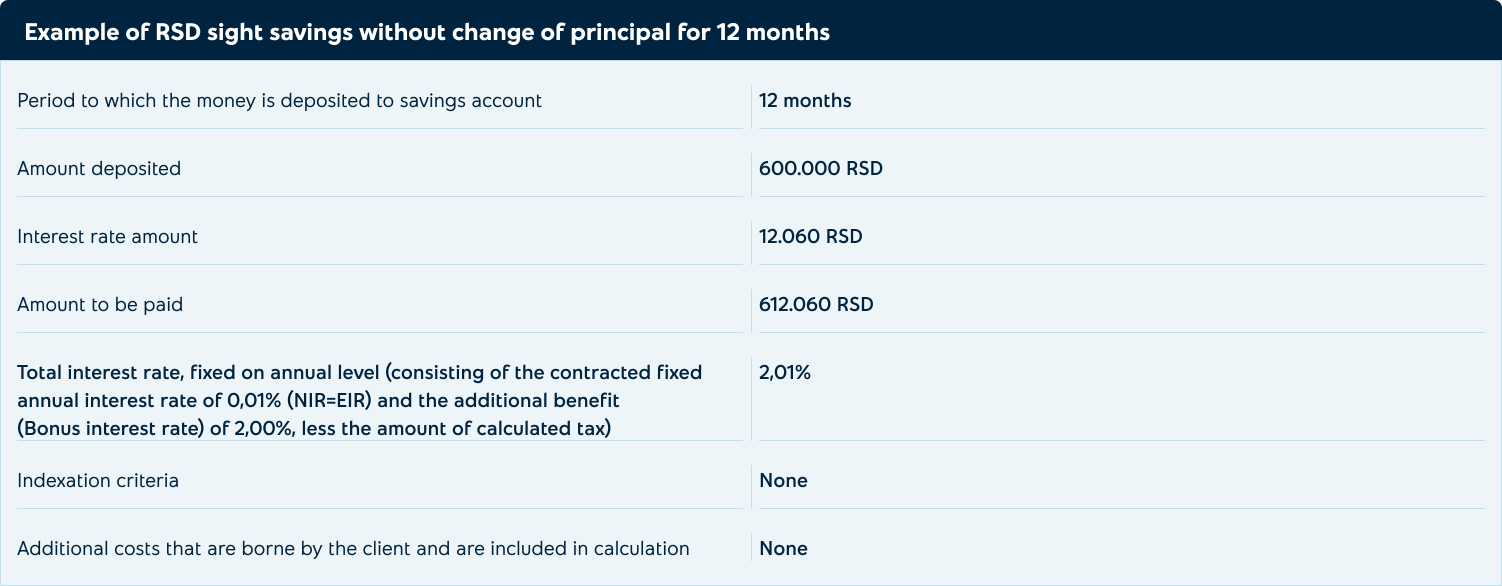
    Representative examples for the 2.01% interest rate in the standard offer

    Representative example of Yettel Bank savings without change of principal for 12 months

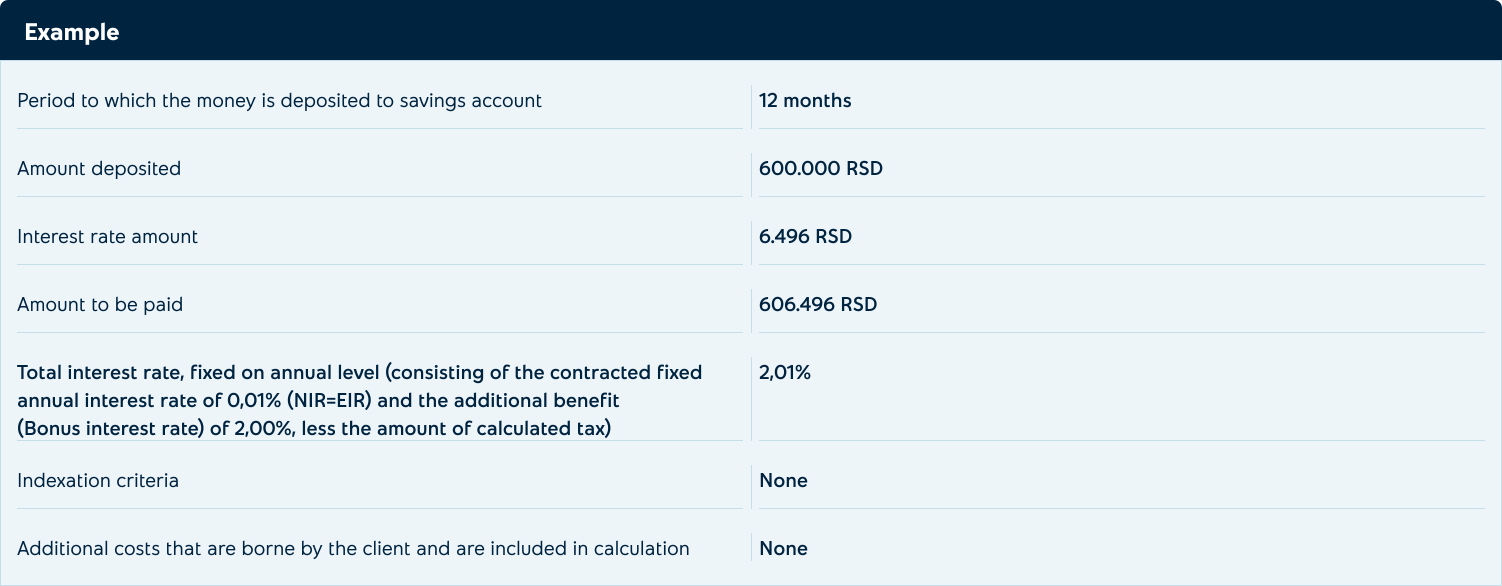
    Example of RSD sight savings without change of principal for 12 months


    The example was made on the assumption that the money was deposited to a savings account on 6th of August 2025. The example was made on the assumption that the additional benefit in the form of Bonus Interest remains unchanged in the period for which the calculation was made.

    In the example shown, the savings interest is calculated on the assumption that the account balance remains unchanged for 12 months, without any increase or decrease in deposits. No tax is applied to interest on savings in dinars.

    Example was created by applying the contracted NIR and Bonus interest rates, which are calculated and paid together.

    Example of Yettel Bank savings, assuming the deposit is fixed for a one-year period and paid out in twelve equal monthly installments.

    Example of Yettel Bank savings, assuming the deposit is fixed for a one-year period and paid out in twelve equal monthly installments, 

    The example was made on the assumption that the money was deposited to a savings account on 6th of August 2025. The example was made on the assumption that the additional benefit in the form of Bonus Interest remains unchanged in the period for which the calculation was made.

    In the example shown, the savings interest is calculated on the assumption that the account balance remains unchanged for 12 months, without any increase or decrease in deposits. No tax is applied to interest on savings in dinars.

    Example was created by applying the contracted NIR and Bonus interest rates, which are calculated and paid together.

    Useful information

    Apply Online

    If you do not have a current account with Yettel Bank — visit the Yettel shop or our branch, open a Bank Lite account (free of charge) and start saving.

    If you have a current account — simply open your savings account online.

    5 Reasons for Sight Deposits?

    • Your money is always available, and you can transfer funds from your savings to your current account at any time. 
    • There is no minimum, nor maximum amount that can be deposited. 
    • You can have more than one savings account. 
    • Interest is calculated and credited at the end of each month or at the time of interruption of savings, whereby the money is transferred to the current account, noting that no tax is paid on the income from interest on savings in RSD.
    • The condition for opening a sight deposit account is an active current account with our Bank (it is enough to have a Bank Lite account that is free of charge), as well as an active (mobile or web) Yettel Bank application that you will use to activate the savings account.

    You're probably wondering...

    How can I start sight savings?

    If you don’t have an account with our Bank, first open a payment account and then start your savings. If you already have an account with our Bank, you can open your RSD term deposit account straight away through internet or mobile app.

    What do RSD sight deposits involve?

    RSD sight deposits are a type of savings where clients conclude an indefinite-term contract with our Bank and where clients can make deposits or withdrawals of funds at any time and where the calculation and accrual of interest is carried out at the end of each month. In our Bank it is possible to have more than one savings account, and you can deposit any amount in each of them (there is no minimum or maximum amount).
    The condition for opening a sight deposit account is an open current account with our Bank (it is enough to have a Bank Lite account that is free of charge), as well as an active (mobile or web) Yettel Bank application that you will use to open the savings account.

    How can I deposit money into my savings account?

    You can deposit funds by making an internal transfer from your current account to a savings account or by buying/selling currency through the exchange office and transferring the converted funds from your current account to the sight deposit account in the currency in which the deposit is kept.
    You can deposit money into your current account at the Yettel Bank ATM and transfer it from the current account to the savings account by internal transfer.
    If you have an exact plan of how much money you want to spend on savings and how often, you can use the application to make a standing order that will automatically transfer you money at intervals you choose – regardless of whether you’re saving in dinars or euros.

    What if I want to withdraw money?

    If you need money, you can immediately get it back to your current account and use the option “withdraw funds” in your savings account details, or through an internal transfer by choosing a savings account from which you want to withdraw money into your current account. Funds from a multi-currency account can always be withdrawn at ATMs or the Bank’s counter. Funds from interest are available after the calculated interest is calculated, which is done on the last day of the month.
    Deposits and withdrawals from ATMs directly to and from a savings account are not possible, and should be made through a current account. The client can withdraw up to 600.000 RSD without notice. You will need to give notice to the bank if you want to withdraw larger amounts regardless of the type of account.
    Note: Direct deposits to a savings account and withdrawals from a savings account via an ATM are not possible.

    How can I manage my Yettel Bank savings?

    You can manage your savings easily and entirely online, with everything always at your fingertips:

    • Your money is always accessible, and your savings grow month after month as long as you leave your deposited funds and earned interest in your account.
    • Flexible instant access savings, with no minimum or maximum deposit amount and no fixed term.
    • Easy savings account opening directly through the mobile app.
    • The option to open and name multiple savings accounts according to your preferences.

    What do the 0.01% interest rate and the Bonus interest rates of 2.00% and 4.00% represent?

    The 0.01% interest rate is the contractual nominal interest rate, guaranteed for an unlimited period, as the savings product itself has no fixed term.

    The 2.00% rate represents an unconditional benefit in the form of an additional (Bonus) interest rate, which the Bank applies to customers who have opened a RSD instant access savings account on or after September 1, 2025.

    For customers who receive their full salary or part of it into their Yettel Bank account and open a new RSD instant access savings account on or after October 28, 2026, the additional (Bonus) interest rate is 4.00%.

    The interest rate applied to your deposited funds is always the sum of the contractual nominal interest rate and the Bonus interest rate, representing the effective interest rate.

    What interest rate will apply when I open a Yettel Bank savings account through the mobile app?

    Under the standard offer, the interest rate applied to your deposit is 2.01% per annum, consisting of the contractual nominal interest rate of 0.01% and an additional (Bonus) interest rate of 2.00%.

    If you receive your full salary or part of it into your Yettel Bank account and open a savings account on or after October 28, 2026, the applicable interest rate will be 4.01% per annum, consisting of the contractual nominal interest rate of 0.01% and an additional (Bonus) interest rate of 4.00%.

    The 4.01% interest rate is available in the latest version of the Yettel Bank app. The interest rate applicable to you will be displayed before you confirm the opening of your savings account.

    How long does the new bonus savings last? Can I expect a change in the interest rate as early as in 2 months?

    Considering that interest rates depend on a very large number of factors on the financial market, we have designed the product in such a way that you do not have to open new savings accounts, and always have conditions that reflect this situation at a certain point in time. Considering that the product has no expiration date, our goal is that the interest rate we give is always at the top of the a-vista savings offers. In this regard, if there is a rise or fall in interest rates on the market (reference interest rate of NBS, Belibor, Euribor), the Bank may decide to change the amount of unconditional benefit in the form of additional (Bonus) interest. Changes of this type, in accordance with the Agreement, also imply notifying clients about the upcoming changes 30 days in advance. We remind you that with such a product you have complete freedom of holding funds without any consequences if for any reason the offer does not suit you.

    What happens in the event of a possible change or cancellation of the additional bonus interest benefit?

    In case of possible change or cancellation of the unconditional benefit in the form of additional (Bonus) interest, the Bank will notify you at least 30 days in advance, indicating the status of the benefit we provide.

    Why does the calculator in the mobile app show a lower interest amount, as if the interest rate were half of the actual rate?

    For instant access savings, the amount of interest you receive depends on the amount of money you keep in your account, the savings period, and the applicable interest rate. Since this savings product allows you to deposit and withdraw funds at any time and has no fixed term, there are countless possible outcomes depending on how you manage your funds.

    To help customers understand how much interest they can expect to receive over a given period, the Decision on the Terms and Method of Calculating the Effective Interest Rate and the Form and Content of Documents Provided to Customers prescribes a specific method for displaying the effective interest rate for this type of savings. The calculation assumes that you withdraw 1/12 of your initial deposit each month, gradually reducing the principal on which interest is calculated. This is why the amount displayed in the app is lower.

    However, if you do not withdraw any funds, interest will be calculated on your entire deposited amount. Please also note that accrued interest is added to your savings balance, meaning you will earn interest on that amount as well, provided you leave it in your account.
    We participate in the mandatory deposit insurance system established in the Republic of Serbia.